Rupiah slips as global risks persist
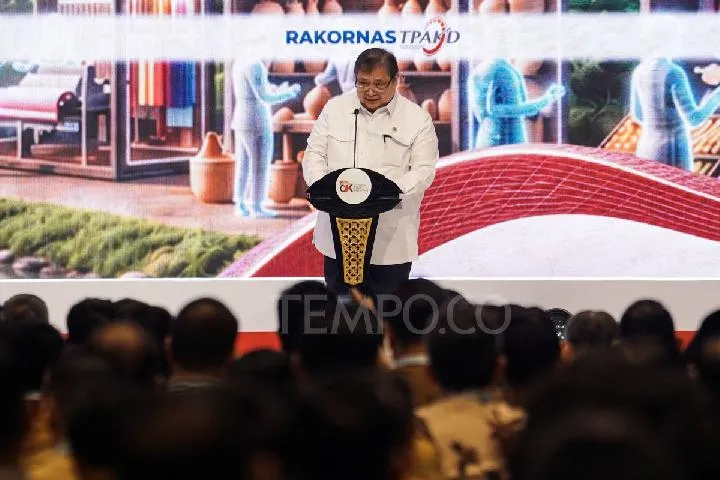
Airlangga expressed optimism about the currency's outlook while acknowledging that its course remained to be seen. Wednesday's close was 28 points, or 0.15 percent, weaker than the previous session's Rp18,156 per dollar. Bank Indonesia's afternoon benchmark, the Jakarta Interbank Spot Dollar Rate (JISDOR), stood at Rp18,183.
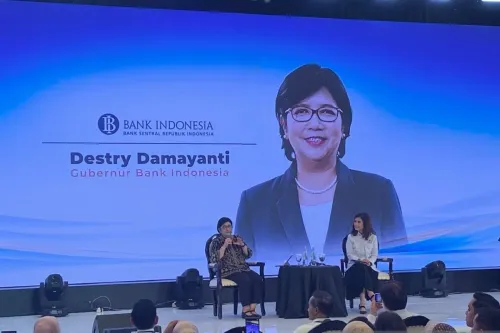
Bank Indonesia (BI) linked pressure on the rupiah and other regional currencies to uncertainty over how the Middle East conflict would be resolved. Erwin Gunawan Hutapea, head of BI's Monetary and Securities Asset Management Department, said the situation was keeping global oil prices above $115 a barrel and raising future fiscal risks. Expectations of a US interest rate increase were also growing, he said.
According to Erwin, investors' increasing aversion to risk strengthened the dollar and prompted capital to leave emerging markets, while bond yields rose. He said the rupiah's performance broadly tracked regional currencies. It had lost 1.15 percent on a monthly basis.
At home, Erwin cited two additional sources of pressure: concerns about a possible MSCI downgrade of Indonesia's stock market classification, which weighed heavily on capital flows, and a surge in domestic demand for foreign currency near the end of the month.
MSCI weighs move to Standalone status
The classification concerns follow MSCI's October 15, 2026, announcement, made on New York time, opening a consultation on moving the MSCI Indonesia Indexes from Emerging Market to Standalone Market status. Market participants can submit feedback through April 30, 2027. MSCI plans to issue its final decision no later than June 30, 2027.
MSCI attributed its proposal to persistently opaque shareholding structures and suspected coordinated trading. It said feedback from market participants suggested that a move to Frontier Markets "would not properly recognize the depth of the market problems." The provider expects to adopt Standalone status unless the consultation produces clear evidence of material improvements in market governance and functioning.
While the consultation proceeds, MSCI is retaining its existing freeze on certain index-related changes for Indonesian securities until further notice. It will not raise Foreign Inclusion Factors (FIF) or Number of Shares (NOS), add securities to the MSCI Indonesia Investable Market Index (IMI), or move securities into larger size-segment indexes.
Budget exposure and earlier declines
The 2026 State Budget uses an exchange-rate assumption of about Rp16,500 per dollar. A Finance Ministry sensitivity calculation cited by Kompas puts the effect of each Rp100 depreciation at roughly Rp5.3 trillion in additional state revenue and Rp6.1 trillion in additional spending, widening the deficit by about Rp800 billion.
The latest weakness follows an 11.04 percent depreciation over the first 1.5 years of President Prabowo Subianto's administration, according to Kompas. The exchange rate moved from Rp15,560 per dollar on October 20, 2024, to Rp17,278 on April 24, 2026. Kompas attributed that decline mainly to external geopolitical dynamics.
For historical context, Kompas reported that the rupiah plunged about 690 percent during the 1997-1998 Asian financial crisis, moving from Rp2,441 per dollar in June 1997 to around Rp17,000 between January and June 1998. The current exchange rate above Rp18,000 per dollar is therefore already weaker than the currency's 1998 crisis low.
BI continues intervention as reserves hold steady
Indonesia's foreign exchange reserves remained stable at $146.3 billion at the end of September 2026. BI said that amount could cover 5.3 months of imports, or 5.2 months of imports together with government external debt servicing. Both measures were well above the international adequacy benchmark of about three months of imports, according to the central bank.
BI said it remains active in currency markets to support orderly trading and keep the rupiah stable in line with economic fundamentals. Its ongoing stabilization operations use Non-Deliverable Forward (NDF), Domestic Non-Deliverable Forward (DNDF), and spot transactions. The bank also continues buying Government Securities (SBN) in the secondary market.
"Bank Indonesia continues to coordinate and communicate intensively with corporations, market players, and other relevant stakeholders," Erwin said.